
Starting a business has become an attractive goal for aspiring entrepreneurs, professionals, and young innovators who want to turn their ideas into practical solutions. From technology platforms and digital services to food businesses and sustainable products, new ventures are emerging across different industries. However, building a successful business requires more than an exciting idea. Entrepreneurs must understand customer needs, evaluate market opportunities, manage financial resources, and develop a clear strategy for long-term growth. With changing consumer expectations and rapidly evolving technology, careful planning has become increasingly important for anyone entering the business world.
A startup company typically begins with a business idea that aims to solve a particular problem, serve an underserved market, or introduce a better way of delivering an existing product or service. Unlike an established organization with proven revenue streams and established customers, a new venture often operates with limited resources and considerable uncertainty. Founders must test assumptions, learn from customer feedback, and adjust their strategies as they discover what works. This process can be challenging, but it also allows entrepreneurs to experiment, innovate, and build businesses around genuine market demand.
Understanding the essential stages of business development can help founders make informed decisions before investing substantial time or money. From choosing the right business model to building a capable team and developing a marketing strategy, every decision influences the venture’s future. A structured approach allows entrepreneurs to reduce avoidable risks, identify opportunities earlier, and create a business that can adapt to changing market conditions.
What Is a Startup Company?
A startup is a newly established business created to develop a product, deliver a service, or solve a problem in a market. Many startups aim to introduce something innovative or establish a business model that can grow beyond its initial customer base. However, innovation does not always mean inventing entirely new technology. It can also involve improving an existing service, making a product more affordable, simplifying a complicated process, or serving customers who have been overlooked by traditional businesses.
For example, an entrepreneur might notice that small retailers struggle to track inventory accurately. Instead of creating a large enterprise software system, the founder could develop a simple application that helps shop owners monitor stock, record sales, and identify products that need replenishment. The business would begin by solving a specific problem for a clearly defined group of customers. If retailers find the application useful and are willing to pay for it, the founder can gradually introduce additional features and expand into other markets.
A startup is not necessarily a technology business, and it does not always need outside investment. Some founders begin with personal savings, a small team, and a limited customer base. Others pursue venture capital because their business requires substantial funding to develop technology, manufacture products, or enter multiple markets quickly. The appropriate approach depends on the business model, the size of the opportunity, and the founder’s long-term objectives.
Why Are Startups Important in the Modern Economy?
Startups contribute to economic development by introducing new products, creating employment opportunities, and encouraging competition. When a new business offers a more convenient or affordable solution, established companies may need to improve their services to remain competitive. This process can benefit customers through better product quality, improved accessibility, and more choices. Startups can also create opportunities for skilled professionals, freelancers, suppliers, and local service providers.
In India, entrepreneurship has gained attention across sectors such as financial technology, education, healthcare, agriculture, logistics, renewable energy, and online commerce. Digital payments and affordable internet access have helped businesses reach customers beyond their immediate locations. A small educational venture, for instance, can offer online tutoring to students in several cities without opening physical classrooms in each location. Similarly, an agricultural technology business can help farmers access market information, monitor resources, or connect with buyers.
Nevertheless, economic contribution depends on building sustainable businesses rather than simply launching new products. A venture must understand its customers, generate sufficient revenue, and manage expenses responsibly. Businesses that combine useful innovation with practical financial planning are better positioned to create lasting value for their customers, employees, and communities.
How to Start a Business From Scratch
1. Identify a Real Market Problem
The first step is to identify a problem that customers genuinely want to solve. Entrepreneurs sometimes begin with a product idea and then search for people who might purchase it. A more reliable approach is to study customer difficulties, existing alternatives, and unmet needs before committing significant resources. Conversations with potential buyers, observation of everyday challenges, and analysis of customer reviews can reveal opportunities that are not immediately obvious.
For example, a founder interested in launching a healthy meal service should investigate local eating habits, delivery expectations, preferred price ranges, and competitors. Customers might want nutritious meals, but they may also care about portion sizes, delivery reliability, and convenient ordering. Understanding these priorities helps the entrepreneur create an offer that addresses practical needs instead of relying on assumptions.
2. Research the Market and Competitors
Market research helps determine whether enough potential customers exist to support the proposed business. Founders should examine the size of their target audience, customer purchasing behavior, competitors, pricing structures, and industry developments. They should also identify indirect competitors because customers may already solve the same problem through a different product or service.
A startup company can conduct early research without purchasing expensive reports. Surveys, interviews, small pilot projects, and public industry information can provide useful initial insights. The objective is not to predict the future perfectly but to understand the market well enough to make informed decisions. If research reveals that customers are unwilling to pay the expected price, the founder can revise the offer before investing heavily in development.
3. Choose a Suitable Business Model
A business model explains how a venture creates value, delivers it to customers, and earns revenue. Some businesses sell individual products, while others charge service fees, monthly subscriptions, transaction commissions, licensing fees, or usage-based prices. The model should match customer expectations and the actual costs of providing the product or service.
For example, a project management application could charge customers a monthly subscription, while a graphic design freelancer might charge per project. A physical product business may earn revenue from direct sales or wholesale distribution. Founders should estimate how much it costs to acquire customers, deliver each sale, provide customer support, and maintain operations. A business that attracts many users but loses money on every transaction may struggle to survive unless it has a credible path toward improving its economics.
4. Prepare a Practical Business Plan
A business plan outlines the venture’s objectives, target market, product offering, pricing strategy, operating requirements, marketing activities, and financial expectations. It helps founders organize their thinking and communicate their plans to potential investors, lenders, partners, or employees. The document does not need to be complicated, particularly when the business is still in its early stages.
The most useful plan identifies major assumptions and explains how they will be tested. Entrepreneurs should estimate initial setup expenses, monthly operating costs, expected revenue, and the amount of cash needed to continue operating during slower periods. They should also establish realistic milestones, such as completing a prototype, gaining the first paying customers, or reaching a specific monthly revenue level. Reviewing these milestones regularly allows founders to adjust their plans when actual results differ from expectations.
Choosing the Right Legal Structure and Completing Registration
Selecting an appropriate legal structure is an important step in establishing a business. In India, entrepreneurs may consider structures such as a sole proprietorship, partnership firm, limited liability partnership, or private limited company. Each option has different implications for ownership, personal liability, taxation, compliance requirements, and fundraising. A sole proprietorship may suit an individual testing a small service business, while a private limited company may be more appropriate for founders planning to bring in equity investors. The best choice depends on the venture’s size, risk profile, ownership arrangements, and future ambitions.
Registration requirements vary according to the selected structure and the nature of the business. Founders may need to obtain a suitable business name, complete incorporation or registration formalities, secure tax registrations where applicable, and arrange industry-specific permissions. Businesses selling regulated products or providing certain services may face additional requirements. It is advisable to verify current rules before beginning operations and seek professional advice when ownership, taxation, or regulatory obligations are complex. Registering correctly from the beginning can help prevent administrative difficulties as the business grows.
The following table summarizes common business structures in India.
| Business structure | Main characteristic | Suitable situation |
|---|---|---|
| Sole proprietorship | Owned by one individual | Small businesses and independent professionals |
| Partnership firm | Owned by two or more partners | Businesses operated jointly by partners |
| Limited liability partnership | Separate legal structure with limited liability for partners | Professional services and collaborative ventures |
| Private limited company | Separate legal entity with a formal shareholding structure | Businesses planning structured expansion or equity investment |
The legal and compliance implications of each structure should be reviewed before making a final decision. For example, a private limited company generally involves more formal reporting and corporate compliance than a simple proprietorship, but its structure can make equity ownership and investment arrangements easier to organize.
How to Fund a New Business
Funding is one of the most important considerations for founders because even a promising idea requires money to develop, market, and deliver its offering. Common expenses include equipment, software, product development, employee salaries, advertising, rent, professional services, and working capital. Entrepreneurs should estimate these expenses carefully and determine how much funding is required to reach their next meaningful milestone. Raising too little can create cash shortages, while raising too much before validating demand may encourage unnecessary spending.
A startup company can use personal savings, revenue from early customers, loans, grants, incubator programs, angel investment, or venture capital, depending on its circumstances. Bootstrapping allows founders to maintain greater ownership and control, although growth may be slower. External investors can provide capital, expertise, and industry connections, but they may expect ownership in return and influence over major business decisions. Loans require repayment and may involve interest or collateral, making them unsuitable for some early-stage ventures without predictable cash flow.
Founders should select funding based on the business’s actual needs rather than assuming that every new venture must attract investors. A consulting service, for example, might begin with a laptop, professional skills, and a few paying clients. A hardware business may need substantial capital before its first sale because product design, manufacturing, testing, and distribution can be expensive. Matching the funding approach to the business model can help entrepreneurs maintain financial flexibility.
Building a Product Customers Actually Want
Product development should focus on solving the problem identified during market research. Instead of attempting to launch a complete product with every possible feature, founders can create a minimum viable product, or MVP. This is an early version containing the essential functionality needed to test whether customers find the solution useful. An MVP may be a basic software application, a small batch of physical products, or a limited service offered to a selected group of customers.
Customer feedback should guide improvements throughout development. Founders can observe how people use the product, identify recurring complaints, and determine which features customers value most. If users repeatedly struggle with a complicated registration process, simplifying that process may deliver more value than introducing additional features. Likewise, a food business may discover that consistent delivery and reliable quality matter more to customers than a large menu. These findings help businesses direct their resources toward improvements that influence customer satisfaction and retention.
Testing also helps reduce the risk of building something that attracts attention but generates few sales. Positive comments are useful, but actual purchasing behavior offers stronger evidence of demand. Entrepreneurs should therefore look for measurable signals, such as paid orders, repeat purchases, product usage, referrals, and customer willingness to recommend the offering.
Creating a Strong Marketing Strategy
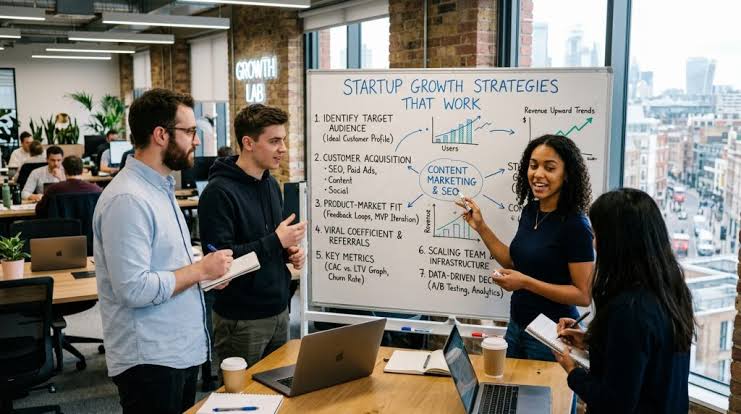
Marketing helps a business reach its intended audience, explain its value, and convert interest into sales. A new venture should first identify its ideal customers, including their needs, budgets, purchasing habits, and preferred communication channels. This understanding makes it easier to choose relevant marketing activities instead of spending money across platforms that do not reach likely buyers.
Digital marketing offers several options for small businesses, including search engine optimization, social media content, email campaigns, educational articles, online advertising, and partnerships with relevant creators. For example, a business selling accounting software to small retailers might publish practical guidance about expense tracking, inventory records, and financial planning. Such content can attract people who are already searching for solutions to related problems. A local bakery, on the other hand, may benefit more from location-based visibility, customer reviews, community events, and attractive product photography.
Marketing should communicate a clear benefit rather than rely on exaggerated claims. Customers need to understand what the product does, how it addresses their problem, and why it deserves their attention. Founders should track results such as qualified leads, conversion rates, customer acquisition costs, and repeat purchases. Regular measurement helps identify effective campaigns and prevents limited budgets from being wasted on activities that produce little business value.
Essential Strategies for Managing Daily Operations
Good operational management enables a business to deliver consistent quality while controlling expenses. Founders must establish practical processes for fulfilling orders, responding to customer questions, maintaining records, managing suppliers, and handling payments. As the business expands, informal arrangements that worked with a few customers may become unreliable. Documented processes help employees understand their responsibilities and reduce dependence on the founder for every routine decision.
A startup company should also use appropriate digital tools to manage tasks, customer relationships, accounting, inventory, and communication. However, purchasing too many subscriptions can increase costs without improving productivity. Entrepreneurs should begin with tools that solve immediate operational problems and upgrade only when there is a clear business reason. Regularly reviewing expenses, customer complaints, delivery performance, and outstanding payments can help identify issues before they become serious.
The following practices can support smoother operations:
-
Maintain accurate financial records and review cash flow regularly.
-
Set clear responsibilities and measurable goals for team members.
-
Establish consistent standards for product quality and customer service.
-
Review supplier performance, operating costs, and delivery timelines.
-
Protect customer information through appropriate security measures.
These habits are particularly valuable when resources are limited. A business that manages its operations carefully can often serve customers more reliably without increasing its expenses at the same rate as its revenue.
Hiring the Right Team and Developing Leadership
The people behind a business have a major influence on its performance. In the early stages, founders often handle several responsibilities, including product development, sales, customer support, and financial planning. As demand increases, it becomes important to identify tasks that require additional expertise. Hiring people with complementary skills can help the business operate more efficiently and allow founders to focus on strategic priorities.
A startup company does not necessarily need a large workforce from the beginning. Entrepreneurs can start with a small team, work with freelancers, or use external specialists for activities such as accounting, design, and legal support. The priority should be to recruit people who understand the business’s objectives, communicate effectively, and are comfortable learning as circumstances change. Clear expectations, regular feedback, and fair compensation also help establish a productive working environment.
Leadership is equally important. Founders must make decisions with incomplete information, communicate challenges honestly, and respond constructively when plans fail. Encouraging team members to share ideas can reveal operational improvements that management might otherwise overlook. A healthy workplace culture built around accountability, respect, and continuous learning can become an important advantage as competition increases.
Common Challenges Faced by New Businesses
Building a business involves uncertainty, and even carefully planned ventures can encounter unexpected obstacles. Limited cash flow, intense competition, difficulty acquiring customers, and inconsistent demand are common challenges. Some founders underestimate the time required to generate revenue, while others expand their operations before establishing a reliable customer base. These decisions can place unnecessary pressure on budgets and make it harder to maintain service quality.
The best way to manage uncertainty is to monitor business performance and respond to problems early. Founders should maintain a realistic financial reserve, avoid unnecessary fixed expenses, and review whether their products continue to meet customer needs. They should also distinguish between temporary setbacks and deeper weaknesses in the business model. A disappointing marketing campaign may require a different advertising approach, whereas repeated customer rejection of the product may indicate a need to reconsider the offering itself.
A startup company should treat mistakes as opportunities to learn rather than reasons to abandon planning. However, experimentation must remain financially responsible. Setting spending limits, defining measurable goals, and evaluating results before committing additional resources can help entrepreneurs make better decisions during uncertain periods.
Measuring Growth and Planning for the Future
Business growth should be measured through meaningful indicators rather than attention or popularity alone. Website visits, social media followers, and app downloads can provide useful information, but they do not necessarily demonstrate financial health. Revenue, profit margins, customer retention, repeat purchases, operating expenses, and cash flow often provide a clearer picture of whether a business is developing sustainably.
Founders should choose performance indicators that match their business model. A subscription service may focus on recurring revenue and customer cancellations, while an online retailer may monitor order values, product returns, and delivery costs. Reviewing these figures monthly can help business owners understand what is working and where improvements are needed. Comparing actual results with financial projections also helps identify emerging problems before they threaten operations.
Expansion should follow evidence of sustainable demand. Depending on the business, growth might involve introducing new products, entering another city, improving distribution, developing partnerships, or serving a different customer segment. Each opportunity should be evaluated against the available resources and the potential effect on quality. Expanding too quickly can create operational problems, while refusing to adapt may allow competitors to capture emerging opportunities.
Conclusion
Building a successful business requires a combination of problem-solving, market understanding, financial discipline, and consistent execution. Entrepreneurs must identify genuine customer needs, validate their ideas, choose an appropriate business structure, and develop products that people are willing to purchase. Strong marketing, reliable operations, and a capable team can then help turn an early concept into a sustainable commercial venture. A startup company does not become successful simply because it has an innovative idea or attracts early attention. Long-term progress depends on delivering genuine value, learning from customer feedback, managing money carefully, and adapting to changing circumstances. Founders who focus on measurable progress rather than rapid expansion alone are better prepared to handle uncertainty and build customer trust.