
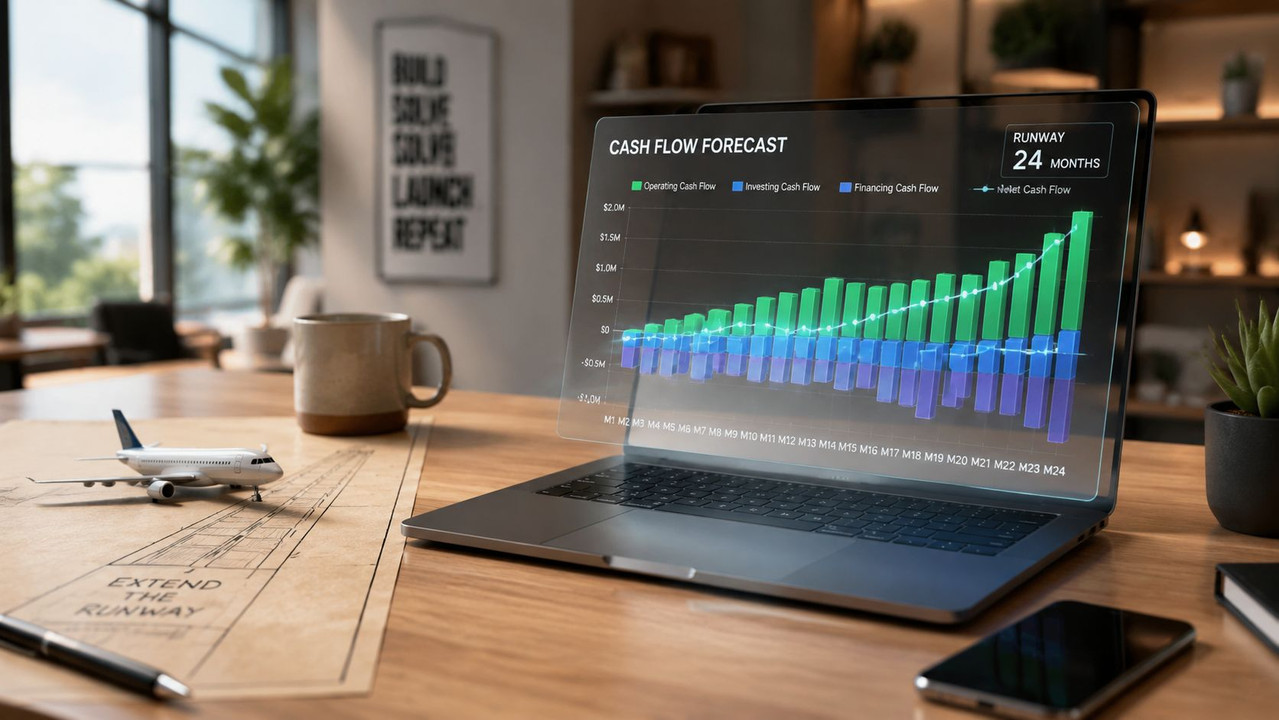
Managing money effectively is one of the biggest challenges for a growing business. Revenue may be increasing, customers may be arriving, and new opportunities may appear regularly, but these positive developments do not automatically mean that a company has enough cash available to operate comfortably. A business can report strong sales and still struggle to pay employees, suppliers, technology providers, rent, taxes, or other essential expenses. This is why startup cash flow planning has become an important part of modern financial management.
Cash flow planning focuses on understanding when money enters a business, when it leaves, and how much remains available for future obligations. Unlike simply looking at revenue or profit, cash flow provides a more practical view of financial liquidity. For a startup operating with limited reserves, even a short period of poor cash management can create serious operational pressure. Careful planning allows founders and managers to identify potential shortages earlier and make informed decisions before financial problems become emergencies.
The current business environment makes this discipline even more valuable. Companies are dealing with changing customer expectations, higher operating costs, unpredictable demand, digital subscription expenses, competitive hiring markets, and rapidly evolving technology. Effective cash management gives businesses the flexibility to respond to these conditions while maintaining financial stability.
Understanding Cash Flow Planning
Cash flow planning is the process of estimating future cash receipts and payments over a specific period. It normally includes expected sales collections, operating expenses, payroll, taxes, supplier payments, loan obligations, technology costs, marketing expenses, and planned investments. By comparing expected inflows with expected outflows, business owners can determine whether sufficient cash will be available at different points in the future.
For a startup, this process should not be treated as a one-time financial exercise. A forecast prepared at the beginning of the year can quickly become inaccurate if sales change, customers delay payments, costs increase, or an unexpected expense appears. A more effective approach is to update forecasts regularly using the latest financial information. This creates a rolling picture of the company’s financial position and helps management respond to changes instead of reacting after a problem has already occurred.
Cash flow planning also encourages businesses to distinguish between accounting profit and actual cash availability. For example, a company might issue invoices worth $50,000 during a month but collect only $20,000 during that period. The remaining amount may technically count as revenue, but it is not immediately available to pay expenses. Understanding this difference is essential for maintaining financial control.
Why Cash Flow Matters More Than Revenue Alone
Revenue is an important indicator of business performance, but it does not necessarily tell management whether the company can meet its immediate financial responsibilities. A business may have impressive sales figures while facing a cash shortage because customers pay slowly or because the company must pay suppliers before receiving customer payments.
Consider a growing software business that signs several large customers on 60-day payment terms. Its monthly sales may look excellent, but payroll, cloud infrastructure, advertising, and office expenses still need to be paid every month. Without sufficient working capital, the company could experience financial pressure despite having a healthy order pipeline.
This is where startup cash flow planning provides a practical advantage. It helps management look beyond sales figures and understand the timing of financial transactions. Knowing that a large payment is expected in two months is useful, but knowing that payroll is due next week is even more important for short-term liquidity management.
Strong cash visibility also improves decision-making. A founder can determine whether the company can afford to hire another employee, increase marketing expenditure, purchase equipment, enter a new market, or invest in a new technology platform. Instead of making decisions based solely on optimism, management can evaluate them against realistic cash projections.
Building a Reliable Cash Flow Forecast
A useful cash flow forecast begins with realistic assumptions. Expected income should be based on actual customer behavior, historical sales patterns, confirmed contracts, realistic conversion rates, and reasonable collection timelines. Overestimating future sales can make a forecast appear healthier than the company’s real position.
Expenses should be estimated with similar discipline. Fixed expenses such as salaries, rent, software subscriptions, insurance, and loan payments are generally easier to forecast. Variable expenses, including advertising, shipping, commissions, production costs, and transaction fees, may require more careful estimation because they can change with business activity.
A practical forecast can be divided into weekly or monthly periods depending on the company’s size and cash position. Businesses with limited reserves may benefit from weekly forecasting because even a small delay in customer payments can have a noticeable impact. As financial stability improves, monthly forecasting can provide a broader strategic view.
Key Components of a Cash Flow Forecast
A reliable forecast generally considers:
- Opening cash balance for the forecasting period.
- Expected customer collections and other income.
- Payroll, supplier payments, taxes, and operating expenses.
- Planned investments, debt payments, and major purchases.
- Closing cash balance after all expected transactions.
The purpose is not to predict every transaction with perfect accuracy. Instead, the objective is to create a useful financial model that highlights possible cash shortages, surplus periods, and important decision points.
Managing Accounts Receivable More Effectively
Customer payment delays can create significant pressure on a growing company. When invoices remain unpaid for weeks or months, the business may need to use its own cash reserves to cover expenses. Improving the collection process can therefore have a direct impact on financial stability.
Businesses should establish clear payment terms before providing products or services. Invoices should contain accurate information, payment deadlines should be easy to understand, and customers should receive reminders before and after the due date. Automated invoicing systems can also reduce administrative delays and make it easier to monitor outstanding balances.
Another useful strategy is to evaluate customer payment behavior. If a particular customer consistently pays late, management can consider adjusting payment terms, requesting deposits, introducing milestone payments, or reassessing the commercial relationship. The goal is not simply to increase sales but to convert sales into usable cash within a reasonable period.
Controlling Operating Expenses
Expense management does not mean cutting every cost. Excessive cost reduction can damage product quality, employee productivity, customer service, or growth potential. The objective is to ensure that every major expense contributes a reasonable amount of value to the business.
Companies should regularly review recurring expenses because small monthly subscriptions can become significant annual costs. Software platforms, unused services, advertising tools, cloud resources, professional subscriptions, and outsourced services should be evaluated periodically.
For example, a company may initially subscribe to several technology platforms while experimenting with different workflows. As the business grows, some of those tools may become unnecessary. Removing redundant expenses can improve cash availability without affecting core operations.
Creating a Practical Expense Review Process
A useful expense review should ask whether a cost is essential, whether its price remains competitive, whether the business is using the service effectively, and whether a less expensive alternative can provide similar value. This approach allows companies to protect important investments while reducing unnecessary financial leakage.
Expense decisions should also consider long-term consequences. Choosing the cheapest option is not always financially intelligent if it creates additional labor, poor reliability, security risks, or customer dissatisfaction. Good financial control balances cost reduction with business performance.
Using Scenario Planning to Prepare for Uncertainty
No cash flow forecast will be completely accurate. Customer demand can change, suppliers can increase prices, projects can be delayed, and unexpected expenses can appear. Scenario planning helps businesses prepare for these possibilities.
A company can create a base scenario representing its most realistic expectations, a stronger scenario based on better-than-expected sales, and a conservative scenario where revenue is lower or payments arrive later. Comparing these scenarios can reveal how much financial flexibility the company actually has.
| Scenario | Revenue Condition | Main Financial Concern | Recommended Focus |
|---|---|---|---|
| Conservative | Lower or delayed sales | Cash shortage | Preserve liquidity and delay nonessential spending |
| Base | Expected performance | Normal operating pressure | Maintain planned spending and reserves |
| Growth | Higher sales and collections | Scaling costs | Invest carefully while protecting working capital |
Scenario planning becomes particularly useful when management is considering a major commitment. Before hiring additional staff or signing a long-term contract, leaders can examine whether the business could still meet its obligations if revenue falls below expectations.
Maintaining an Emergency Cash Reserve
A financial reserve gives a business additional protection against unexpected events. The appropriate reserve level depends on the company’s industry, revenue predictability, operating expenses, access to financing, and business model.
A company with recurring subscription revenue may have more predictable cash inflows than a business dependent on occasional large contracts. Similarly, a company with high fixed expenses may require a larger reserve than a lean operation with flexible costs.
The reserve should be treated as a financial safety mechanism rather than ordinary spending money. Its purpose is to provide time and flexibility when circumstances change. A sudden customer loss, equipment replacement, legal expense, economic slowdown, or delayed payment can become much easier to manage when the company has accessible cash available.
Technology and Modern Financial Control
Technology has changed how businesses monitor their finances. Cloud accounting platforms, automated invoicing, digital payment systems, expense management software, and financial dashboards can provide management with faster access to important information.

However, technology alone does not create good financial management. A business can have sophisticated financial software and still make poor decisions if its forecasts are based on unrealistic assumptions. Technology should support a disciplined process rather than replace financial judgment.
Modern businesses can also connect financial information from different operational areas. Sales data, invoice status, payroll costs, subscription expenses, inventory information, and bank transactions can provide a more complete picture of financial health. When this information is reviewed regularly, management can identify trends before they become serious problems.
How Startup Cash Flow Planning Supports Growth
Growth requires investment, but uncontrolled growth can create financial stress. Hiring employees, increasing inventory, expanding marketing, entering new markets, and developing new products all require cash. If expansion happens faster than the company’s ability to finance it, operational difficulties can emerge.
Startup cash flow planning helps management determine whether growth initiatives are financially sustainable. Instead of asking only whether an opportunity can increase revenue, leaders can consider when the investment will require cash, when additional revenue is likely to arrive, and how much financial pressure the business can handle during the transition.
This approach is particularly important for companies experiencing rapid growth. Higher sales may require more inventory, larger teams, additional infrastructure, and greater customer support capacity. Consequently, revenue growth can sometimes increase cash requirements before it improves cash availability.
Common Cash Flow Mistakes Businesses Should Avoid
One of the most common mistakes is relying entirely on bank account balances. A healthy balance today does not necessarily mean that the business is financially secure. Several large payments could be due shortly, and customer collections may not arrive on schedule.
Another mistake is assuming that every sale will be collected immediately. Payment delays should be considered when preparing forecasts. Businesses should also avoid ignoring seasonal patterns. Some industries experience significant differences between high-demand and low-demand periods, which can dramatically change cash requirements.
Other common problems include:
- Mixing personal and business spending.
- Ignoring tax and regulatory payment deadlines.
- Making large purchases without evaluating future cash requirements.
- Failing to update forecasts when actual results change.
Avoiding these mistakes can significantly improve financial visibility. Even simple forecasting becomes valuable when it is updated consistently and connected to real business activity.
Creating a Sustainable Financial Routine
Financial control works best when it becomes part of the normal management routine. Business owners should establish a regular schedule for reviewing expected collections, upcoming expenses, cash reserves, overdue invoices, and major financial commitments.
A weekly review can focus on immediate liquidity, while a monthly review can examine broader trends. Quarterly reviews can then be used for strategic planning, including hiring decisions, pricing changes, investment plans, and expansion opportunities.
The most effective process is one that management can maintain consistently. A complicated financial system that nobody updates is less useful than a simple forecasting process that is reviewed every week. Consistency creates visibility, and visibility creates better financial decisions.
The Strategic Value of Better Cash Management
Cash management is not simply about preventing financial problems. It can also create strategic advantages. A financially disciplined company can respond more confidently when an attractive opportunity appears because management understands how much capital is available and what commitments are already scheduled.
Strong cash control can also improve relationships with suppliers, employees, lenders, investors, and other stakeholders. A company that consistently meets its financial obligations demonstrates operational discipline and reliability. Over time, this can support better negotiating positions and stronger business relationships.
For founders, financial visibility also reduces uncertainty. Instead of constantly wondering whether enough money will be available next month, they can use reliable information to plan hiring, marketing, product development, and expansion. This allows financial management to become a strategic tool rather than merely an administrative responsibility.
Conclusion
Effective cash management is one of the foundations of sustainable business growth. Revenue and profitability remain important measures, but they do not provide the complete picture of financial health. Understanding the timing of cash inflows and outflows allows management to protect liquidity, prepare for uncertainty, and make better operational decisions. For any startup, disciplined cash flow management can make the difference between reacting to financial pressure and preparing for it in advance. Regular forecasting, careful expense control, stronger collections, scenario planning, and appropriate cash reserves provide a practical framework for maintaining financial stability.
.jpg&description=Learn how startup cash flow planning improves financial control, manages expenses, protects working capital, and supports smarter long-term business decisions.)