
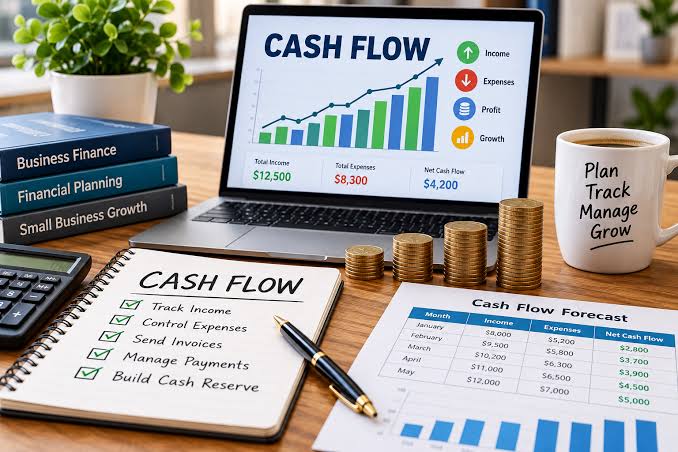
Cash flow planning is one of the most important financial practices for any growing business. A company can have strong sales, promising products, and an expanding customer base, yet still face serious financial pressure if money does not arrive when bills, salaries, taxes, and operating expenses become due. Understanding when cash enters and leaves the business gives founders a clearer view of their actual financial position and helps them make decisions based on available resources rather than assumptions.
For a startup, careful cash management becomes even more important because resources are often limited and revenue can be unpredictable. Early-stage businesses may spend heavily on product development, marketing, technology, hiring, and customer acquisition before they generate consistent income. A practical cash flow plan allows founders to estimate upcoming requirements, identify potential shortages early, and decide where spending should be increased, reduced, or delayed. This creates greater financial control while giving the business room to respond to changing market conditions.
In the current business environment, companies also have to deal with changing customer demand, higher operating costs, competitive pricing, evolving technology, and uncertain economic conditions. A well-designed cash flow process therefore goes beyond simply tracking a bank balance. It connects financial planning with daily business decisions and helps create a more resilient operation.
Why Cash Flow Planning Matters for Financial Stability
Financial stability depends heavily on having enough accessible cash to meet short-term obligations while continuing to invest in future growth. Profit and cash flow are not the same thing. A business may record revenue from a customer but receive the actual payment weeks or months later. During that period, the company may still need to pay employees, suppliers, software providers, landlords, lenders, and other service providers. This timing difference can create financial pressure even when the business appears profitable on paper.
A disciplined startup approach to cash flow planning helps management understand these timing differences before they become problems. Instead of waiting until the bank balance becomes uncomfortable, founders can review expected collections and upcoming expenses regularly. This makes it easier to identify periods where cash may become tight and prepare appropriate responses. For example, a company expecting several large customer payments next month may be able to schedule a major investment with greater confidence, while a business facing delayed collections may postpone non-essential spending.
Another important benefit is better decision-making. When founders understand their cash position, they can evaluate opportunities more realistically. Hiring a new employee, launching a marketing campaign, purchasing equipment, or entering a new market can all affect cash availability. Cash flow planning provides a financial framework for deciding whether an opportunity can be comfortably funded now or should wait until revenue becomes more predictable.
Building a Reliable Cash Flow Forecast
A useful cash flow forecast begins with realistic assumptions. Businesses should estimate expected cash inflows and outflows over a suitable period, commonly several months ahead. The forecast should include customer payments, subscriptions, financing, investments, payroll, rent, technology expenses, marketing costs, taxes, supplier payments, and other recurring or occasional obligations.
Revenue projections should not simply be based on optimistic sales targets. A more reliable forecast considers existing contracts, historical payment patterns, current sales pipelines, seasonal changes, and realistic conversion rates. If customers generally take 30 or 60 days to pay invoices, the forecast should reflect that delay. Similarly, expenses should include both predictable recurring costs and irregular expenses that could affect cash availability.
A startup can improve forecast accuracy by comparing projected figures with actual results every month. If expected customer payments repeatedly arrive later than planned, the forecast should be adjusted. If marketing expenses consistently exceed estimates, that difference should also be reflected in future projections. Over time, this process creates a more dependable financial picture and allows management to identify patterns that might otherwise remain unnoticed.
Forecasting Different Business Scenarios
One forecast may not be enough when market conditions are uncertain. Businesses can create several scenarios to understand how their cash position could change under different circumstances. A base scenario can represent expected performance, while a conservative scenario can assume slower sales or delayed customer payments. A stronger-growth scenario can show what happens if sales increase faster than expected.
Scenario planning is especially valuable when a company is considering significant spending. Suppose a business wants to hire several employees to support expansion. Instead of assuming that additional revenue will immediately cover the cost, management can model what happens if sales arrive three months later than expected. This approach does not discourage investment; it makes the investment more deliberate.
| Cash Flow Area | What to Monitor | Why It Matters |
|---|---|---|
| Customer payments | Timing and outstanding invoices | Determines when expected revenue becomes usable cash |
| Payroll | Salaries, benefits, and hiring plans | Usually one of the most important recurring costs |
| Operating expenses | Rent, software, utilities, services | Helps control regular cash commitments |
| Marketing | Campaign spending and returns | Prevents growth spending from becoming excessive |
| Taxes and obligations | Upcoming payment dates | Reduces the risk of unexpected cash shortages |
Managing Receivables More Effectively
Getting customers to pay on time can have a major impact on financial stability. A business may have strong sales but still struggle if invoices remain unpaid for long periods. Establishing clear payment terms, sending invoices promptly, monitoring overdue accounts, and maintaining professional communication with customers can improve the speed at which revenue becomes available cash.

The process should begin before an invoice becomes overdue. Businesses can establish expectations during the sales process by clearly communicating payment schedules and conditions. Automated reminders can also reduce the administrative burden of following up with customers. For larger contracts, milestone-based payments may help distribute cash collection throughout a project rather than requiring the company to finance the entire project until completion.
For a growing startup, receivables management should become part of normal financial operations rather than an occasional administrative task. Regularly reviewing outstanding invoices helps management identify customers who consistently pay late and understand how those delays affect working capital.
Controlling Expenses Without Limiting Growth
Cash flow planning is not simply about cutting costs. Excessive cost reduction can damage a company’s ability to serve customers, develop products, or compete effectively. The goal is to distinguish between spending that supports sustainable growth and spending that produces limited value.
A company should periodically evaluate whether major expenses are contributing to measurable business outcomes. For example, technology subscriptions that are rarely used may be candidates for cancellation, while essential tools that improve productivity could justify their cost. Similarly, marketing expenditure should be evaluated according to customer acquisition, revenue contribution, and long-term brand value rather than being judged solely by its immediate expense.
For a startup, this balance is particularly important. Early-stage companies often have limited financial reserves, so every recurring commitment should be considered carefully. Instead of automatically increasing fixed costs, management can explore flexible arrangements where practical. This may include variable service contracts, phased investments, or carefully timed hiring decisions.
Creating a Cash Reserve
A cash reserve provides protection against unexpected events. Revenue can fall suddenly, customers can delay payments, equipment can require replacement, or an important project can take longer than expected. Without sufficient liquidity, even a temporary disruption can force a business to make rushed decisions.
Building a reserve should therefore be treated as a strategic financial objective. The appropriate amount depends on the company’s operating model, revenue predictability, fixed expenses, industry conditions, and access to external financing. Businesses with highly predictable recurring revenue may have different requirements from companies whose income changes significantly from month to month.
A practical approach is to gradually increase the reserve as the business becomes more stable. Rather than waiting until the company has accumulated a large surplus, management can establish a habit of retaining part of available cash when conditions permit. This creates a financial buffer that can support operations during weaker periods.
Using Technology to Improve Financial Visibility
Modern financial tools can make cash flow management faster and more accurate. Accounting platforms, invoicing systems, expense management software, payroll tools, and business banking solutions can provide useful information about transactions and upcoming obligations. The value comes not simply from having multiple tools but from creating a consistent process for reviewing the information they provide.
Automation can reduce repetitive work such as invoice reminders, expense categorization, payment tracking, and recurring reporting. However, automated data still requires human interpretation. A dashboard may show that cash has increased, but management needs to understand whether the increase comes from sustainable revenue, temporary financing, delayed expenses, or another factor.
For a startup, financial visibility becomes increasingly valuable as operations grow. When a business has only a handful of transactions, founders may understand its finances through direct observation. As the number of customers, employees, suppliers, and expenses increases, that informal approach becomes less reliable. Structured financial reporting provides a stronger foundation for decision-making.
Building a Regular Cash Flow Review Process
Cash flow planning works best when it becomes a recurring management activity. Reviewing financial information only at the end of a quarter may leave too little time to respond to emerging problems. A regular review can identify changes in revenue, payment timing, expenses, and cash reserves while there is still an opportunity to act.
A practical review should focus on the most important financial movements rather than overwhelming management with unnecessary detail. Founders can compare expected cash inflows with actual collections, review major upcoming payments, examine overdue invoices, and check whether spending remains consistent with the financial plan.
Useful questions during a cash flow review include:
- Are customers paying within the expected timeframe?
- Have recurring expenses increased unexpectedly?
- Are upcoming obligations fully covered?
- Is the current cash reserve appropriate for business risk?
The answers can then guide decisions for the following weeks or months. If collections are slowing, the company may strengthen its receivables process. If expenses are rising faster than revenue, management may review discretionary spending. If cash is stronger than expected, the business can consider whether additional investment or reserve building makes sense.
Preparing for Unexpected Financial Pressure
No forecast can predict every event. A major customer may leave, a supplier may increase prices, a product launch may be delayed, or market demand may change quickly. Financial stability comes partly from preparing for these possibilities before they happen.
A business should understand which expenses are essential and which can be reduced temporarily if revenue declines. It can also identify alternative suppliers, review financing options, and maintain relationships with important business partners. Having these plans in advance makes it easier to respond calmly during periods of pressure.
For a startup, financial flexibility can be as important as revenue growth. A company that grows rapidly while maintaining extremely high fixed costs may become vulnerable if market conditions change. In contrast, a business with controlled commitments and strong visibility into its cash position has greater room to adapt.
Cash Flow Planning and Sustainable Growth
Growth consumes cash. Hiring employees, purchasing inventory, developing products, expanding marketing, and entering new markets often require spending before the resulting revenue arrives. This means growth should be planned alongside liquidity rather than treated as a separate objective.
A healthy startup should ask whether its growth strategy can be funded without creating unnecessary financial stress. If expansion requires substantial upfront spending, management can consider phased implementation. Instead of opening several new markets simultaneously, the company might test one market first, measure results, and then expand using evidence from the initial investment.
This approach makes growth more controlled and measurable. It also helps prevent a common problem in which businesses mistake increasing sales for financial health. Revenue growth is valuable, but sustainable growth requires enough cash to support operations throughout the expansion process.
Common Cash Flow Planning Mistakes
One of the most common mistakes is confusing profitability with liquidity. A business may show positive accounting results while having insufficient cash because customers have not yet paid. Another mistake is failing to account for irregular expenses such as taxes, annual subscriptions, equipment replacement, legal services, or seasonal costs.
Businesses can also become overly optimistic about future sales. Forecasts that assume every potential customer will convert can make the financial position look stronger than it really is. Conservative assumptions generally provide a safer foundation, particularly when the business is operating with limited reserves.
A further mistake is ignoring small recurring expenses. Individual subscriptions or service charges may appear insignificant, but dozens of recurring payments can create a meaningful monthly burden. Reviewing these commitments periodically can reveal opportunities to improve efficiency without affecting core operations.
Conclusion
Cash flow planning is a fundamental part of building financial stability. It gives businesses a clearer understanding of when money will arrive, when it needs to be spent, and how financial decisions could affect future operations. By forecasting realistically, monitoring receivables, controlling unnecessary expenses, maintaining reserves, and reviewing performance regularly, businesses can reduce financial surprises and make more confident decisions.